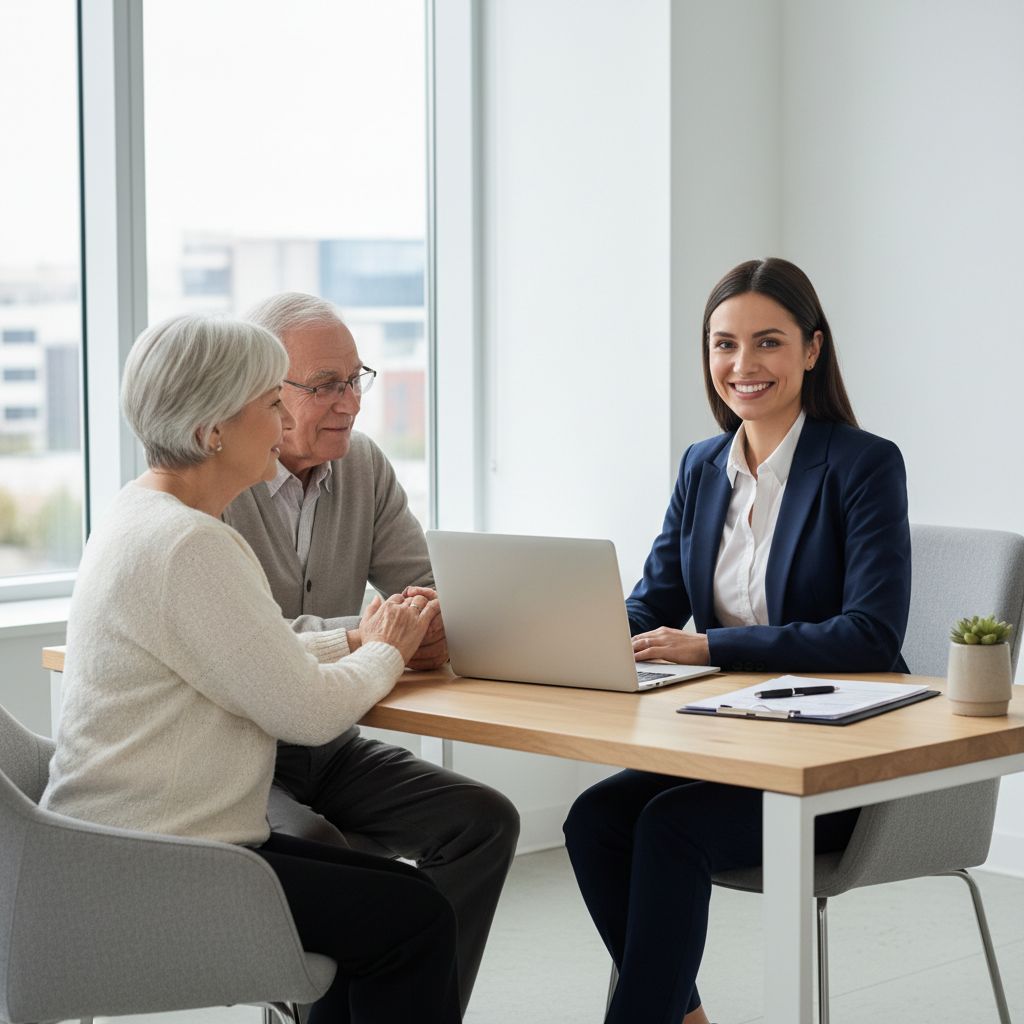

A reverse mortgage is one of the bigger financial decisions a homeowner can make later in life, and it’s not one you want to sort out alone from a stack of brochures. That’s where a reverse mortgage advisor comes in, someone whose entire job is to help you understand whether this path actually makes sense for your situation, and if so, how to move through it without missteps.
What a Reverse Mortgage Advisor Actually Does
Unlike a general loan officer handling a purchase or refinance, a reverse mortgage advisor specializes in a very specific, and often misunderstood, financial tool. Their role starts before any paperwork is signed: walking you through how a reverse mortgage works, what it costs, and how it compares to other ways of accessing your home’s equity, like a home equity line of credit or downsizing altogether.
Once you decide to move forward, the advisor coordinates the required HUD-approved counseling session, helps assemble your documentation, and explains each condition of your loan in terms you can actually follow, not just legal language on a disclosure form. They stay involved well past closing too, since reverse mortgages come with ongoing obligations like maintaining homeowners insurance and staying current on property taxes.
Why This Decision Deserves Specialized Guidance
Reverse mortgages affect your home equity, your estate, and potentially your heirs, which is a lot more permanent than a typical loan decision. A knowledgeable advisor helps you think through questions that are easy to overlook in the excitement of unlocking extra cash flow:
How will this affect what you’re able to leave behind for your family? What happens if you need to move into assisted living down the road? How does this interact with other retirement income or benefits you’re relying on? A good advisor doesn’t just answer these questions, they raise them before you have to ask.
Qualities Worth Looking For
Not every advisor approaches this conversation the same way, and the difference shows up in how they handle your questions. Look for someone who explains both the benefits and the trade-offs honestly, rather than only highlighting the upside. Pay attention to whether they encourage you to loop in family members or a trusted advisor of your own, instead of rushing you toward a decision. And notice whether they’re patient with questions you might ask more than once, since this is unfamiliar territory for most homeowners considering it for the first time.
An advisor who welcomes scrutiny of the numbers, and who is comfortable saying “this might not be the right fit for you,” is usually one worth trusting.
Questions Worth Bringing to Your First Conversation
-
What are the total costs involved, including fees and interest over time?
-
How does my available loan amount get calculated?
-
What are my repayment obligations, and when do they apply?
-
How does this affect my heirs or the future sale of my home?
-
What ongoing responsibilities come with keeping the loan in good standing?
Their willingness to answer clearly, without rushing past the harder questions, tells you a lot about how the rest of the relationship will go.
Final Thoughts on Reverse Mortgage Advisor
A reverse mortgage can be a genuinely useful tool for the right homeowner, but it’s a decision that deserves patience, honest guidance, and someone willing to slow down and make sure you understand every part of it. The right reverse mortgage advisor treats that responsibility seriously. At Sun American Mortgage, our advisors take the time to walk through the full picture with you, so whatever you decide, you’re deciding with confidence.